5 Pros and Cons of Convertible Notes
In this article, we will discuss the basics of convertible notes and explore their pros and cons as well.

Raising capital without a market-validated valuation is one of the common challenges of early-stage startups. Convertible notes emerged as the practical answer to that problem deferring the valuation question until the business has enough traction to support a credible number.
The instrument has evolved significantly over the past decade. SAFEs have taken over pre-seed financing for most U.S. startups, while convertible notes have consolidated into specific use cases bridge rounds, post-Series A extensions, and raises involving investors who require debt-level protections that SAFEs do not offer.
At the same time, the terms on notes have tightened: interest rates have moved up, discount rates have increased on larger deals, and valuation caps have dropped, making it more important than ever for founders to understand exactly what they are signing and what it will cost at conversion.
In this article, the four main terms of a convertible note are broken down, along with how they work together at conversion, where notes fit in the funding landscape in 2026, and five advantages and disadvantages that every founder should think about before issuing one.
Key Takeaways
- Convertible notes are short-term debt that converts into equity at a future priced round, deferring the valuation question entirely at issuance.
- Standard maturity windows are 18-24 months; if no qualifying round occurs, the note is technically due a real risk in today’s elongated fundraising environment.
- SAFEs now dominate pre-seed (81% of deals used cap-only SAFEs in Q1 2025 per Fenwick), while convertible notes remain the preferred instrument for bridge rounds and post-Series A extensions.
- Notes defer dilution, not eliminate it ownership impact is concentrated at conversion and easy to underestimate when multiple notes with different terms are outstanding.
What Are Convertible Notes?
A convertible note is an investment vehicle through which an investor loans money to a startup and receives equity in the company at a future date, rather than cash repayment. Unlike a standard business loan, convertible notes are designed to convert into equity typically at the startup’s next priced funding round at terms that reward the investor’s early risk.
Convertible notes are particularly useful at seed funding stages because they allow both parties to skip the most contentious early negotiation valuation until the company has revenue, customers, and market data to support a credible number.
4 Convertible Note Terms That Affect Founder Dilution
A convertible note is only as valuable or expensive as the terms written into it. The discount rate, valuation ceiling, interest rate, and maturity date all influence how much equity the investor receives at conversion and how much dilution the founder experiences.
Understanding each concept individually is necessary before successfully negotiating them together.
1. Discount Rate
The discount rate compensates early investors for the risk of investing before a formal valuation is set. It applies a percentage reduction to the per-share price of the next priced round. As DLA Piper’s convertible securities guide explains, the longer the period before conversion occurs, the higher the discount is typically set rewarding investors who take on more risk by committing earlier.
A 20% discount means the noteholder converts at $0.80 per share when new investors pay $1.00. The Startup Law Blog confirms that 20% is the most common discount, with 10-25% the standard range.
2. Valuation Cap
The valuation cap sets a ceiling on the valuation used for the note’s conversion protecting early investors if the company’s Series A valuation climbs far above what was implied at the note stage. According to the CRV’s 2026 guide, if a Series A prices above the cap, the noteholder converts as though the company were valued at the cap and receives more shares per dollar than new investors.
When a note includes both a cap and a discount, the investor converts under whichever mechanism yields the greater benefit they do not stack. Fenwick’s Q1 2025 data shows valuation caps dropped on deals above $5M through 2025, a direct cost increase for founders on larger raises.
3. Interest Rate
Convertible notes are legally loans and must accrue interest. Unlike a traditional loan, this interest is not paid in cash it accrues alongside the principal and converts into additional shares at the qualifying financing round, increasing the investor’s share count.
4. Maturity Date
The maturity date is the deadline by which the note must convert through a qualifying financing round or be repaid in cash. The standard window is 18-24 months from issuance. A note that reaches maturity without conversion puts the company in technical default and gives the investor the contractual right to demand repayment.
Most investors negotiate an extension rather than force repayment but that extension conversation happens on the investor’s terms, not the founder’s. Founders should target the longest maturity date possible and begin extension discussions at least three to six months before the deadline.
How Do Convertible Notes Work?
The cost of a convertible note changes based on which combination of terms is applied. The table below illustrates this using a $250,000 convertible note with an 18-month maturity and a hypothetical Series A at $5M pre-money, priced at $1.00/share, based on current 2026 market-rate terms according to Fenwick’s Q1 2025 Venture Beacon.
table
Source: Eqvista calculations using 2026 market-rate benchmarks. Per J.P. Morgan (July 2026), when both cap and discount apply, the investor receives whichever mechanism is more favorable, not both stacked.
Conversion Example
The following example illustrates how conversion mechanics play out under current 2026 terms:
A health-tech startup raises a $500,000 convertible note. Terms: 6% annual interest, $10M valuation cap, 20% discount. Twelve months later, it raised a Series A at a $35M pre-money valuation, priced at $2.00 per share. At that price, the company has 17.5 million shares outstanding pre-money ($35M pre-money valuation ÷ $2.00 per share = 17,500,000 shares).
- Principal + accrued interest: $500,000 + $30,000 = $530,000
- Discount path: $2.00 × 80% = $1.60/share → $530,000 ÷ $1.60 = 331,250 shares
- Cap path: The $10M valuation cap is applied to the same share count: $10M ÷ 17,500,000 shares = $0.571/share → $530,000 ÷ $0.571 = 928,196 shares
Result: The cap path applies (more favorable to the investor). The investor receives 928,196 shares at $0.571 each. At the Series A price of $2.00, those shares carry a paper value of approximately $1.86M a 3.7x return on a $500K check in 12 months. As J.P. Morgan notes, this illustrates why caps are the primary dilution driver for founders, not the headline discount rate.
How Startups are using Convertible Notes Stand in 2026
The early-stage instrument market has bifurcated. According to Fenwick’s Q1 2025 Venture Beacon, cap-only SAFEs were used in 81% of deals in Q1 2025 (up from 76% in 2024). SAFEs have taken the pre-seed stage by a wide margin; they carry no interest and no maturity date, eliminating the two structural risks that convertible notes create for founders.
Convertible bridge rounds remain common among post-Series A companies looking to avoid priced rounds in a volatile market where notes retain a clear structural advantage.
The key practical difference is what each instrument assumes about what happens next. A SAFE assumes a priced round will occur there is no maturity date, no repayment obligation. A convertible note assumes a priced round might not occur on schedule, and the maturity date creates a legal debt claim if the company falls short. In 2026’s fundraising environment, where Series
A diligence timelines have extended and bridge rounds have become more common, that structural distinction matters more than it did in prior years.
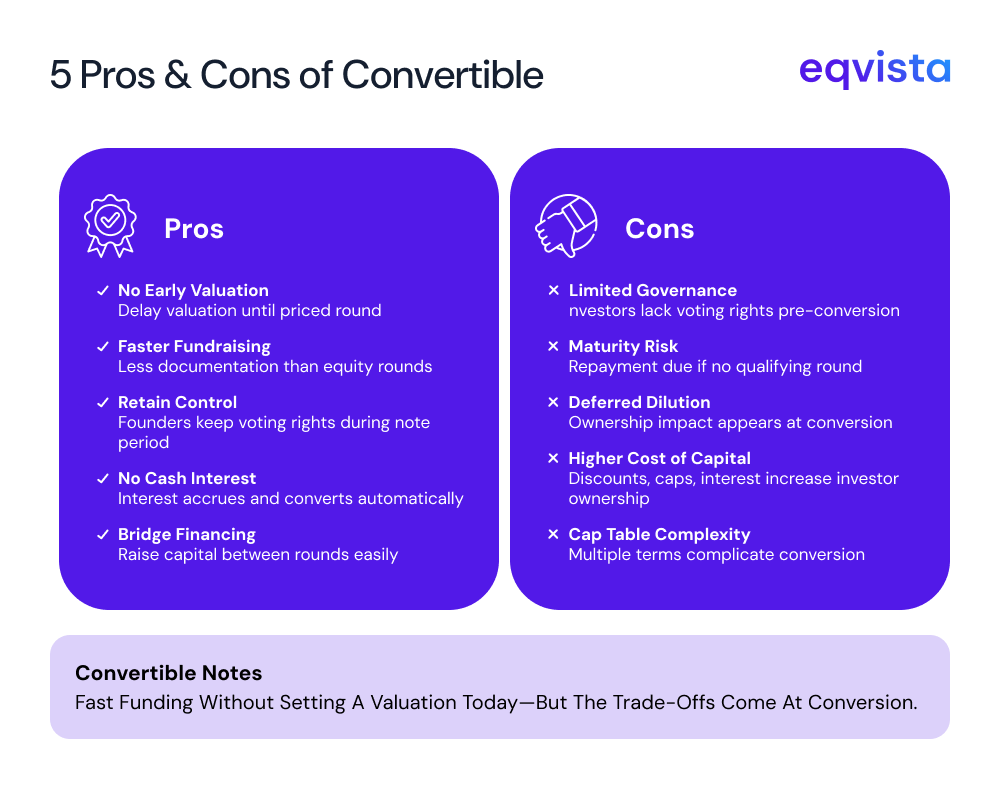
5 Pros of Convertible Notes
Convertible notes have remained a staple of early-stage financing for good reason. They solve real problems: they let founders raise capital fast, avoid premature valuation, and retain control at a stage when the business is still finding its footing. The five advantages below reflect what the instrument does well when it is used in the right context and structured with clear terms.
No Valuation Required at Issuance
The most fundamental advantage of a convertible note is that it allows a startup to raise capital without setting a valuation. Early-stage companies are genuinely difficult to value: there may be minimal revenue, limited comparables, and a market that is still being defined. A full priced equity round requires detailed documentation, extensive legal work, and a defensible valuation costs that run into tens of thousands of dollars in legal fees alone.
A convertible note defers that entire process, letting founders close a round in days and redirect attention to product and growth. This is the decisive advantage when a founder needs capital now and valuation data later.
Faster Closing and Simpler Documentation
The documentation required for a convertible note is significantly lighter than a priced equity round. Standard convertible note templates can be adapted in days, not weeks. There is no certificate of incorporation negotiation, no investor rights agreement, and no shareholder agreement to draft from scratch. This speed advantage is most valuable when a company is approaching a near-term milestone: a product launch, a pilot customer, or a regulatory clearance that will materially change its valuation.
Closing on a note before that milestone and pricing equity after it is often the optimal capital structure for early-stage companies.
Founders Retain Voting Control During the Note Period
Convertible noteholders are creditors, not equity holders, until conversion. That means they do not hold voting rights on corporate matters during the note period, no board seats, no shareholder votes, no approval rights on major decisions.
For founders who are sensitive about maintaining decision-making control in the early stages, particularly when negotiating with multiple angels or micro-funds simultaneously, this is a meaningful structural advantage. It also means the company avoids granting investor information rights or approval thresholds at a stage when the business may still be finding its strategy.
Interest Accrual Increases the Investor’s Return Without Immediate Cash Cost
Convertible notes accrue interest, but unlike a bank loan, that interest does not require cash payment during the note’s life. It adds to the principal amount that converts at the qualifying round, increasing the investor’s final share count.
This gives early investors a creditor-level financial protection a floor on their investment outcome while keeping the company’s cash available for operations.This feature is particularly valued by investors whose fund mandates require yield-bearing instruments, such as certain family offices that cannot legally hold SAFEs.
Effective Bridge Instrument Between Priced Rounds
Convertible notes are the preferred instrument for bridge rounds situations where a startup between priced rounds needs short-term capital to reach its next milestone without triggering a new valuation event.
Fenwick’s Q1 2025 Venture Beacon confirms that convertible bridge rounds remain common among post-Series A companies looking to avoid priced rounds in a volatile market. The maturity date on a bridge note also creates a natural defined deadline: both the company and the investor have a defined deadline, which introduces discipline around reaching the milestone that will support the next priced round.
In a market where uncertainty is high and priced round timelines have extended, that structure is often exactly what both parties need.
5 Cons of Convertible Notes
No funding instrument is without trade-offs, and convertible notes carry several that founders consistently underestimate. The five disadvantages below are not edge cases; they are the most common sources of friction that emerge when notes are issued without modeling the downstream consequences, and they become more acute as tightening 2026 terms shift the balance toward investors.
Investors Have No Governance Rights or Visibility During the Note Period
The same structural feature that benefits founder noteholders having no voting rights is a drawback from the investor’s perspective. A convertible noteholder is a creditor with a future equity claim, not a current equity holder. They have no board seat, no information rights, and no formal input on strategic decisions until conversion.
For first-time investors entering a startup, this means making a significant financial commitment without the governance visibility that priced equity rounds provide. The governance layer comes at conversion not at the moment the check is written.
Maturity Risk in a Slow Fundraising Environment
A convertible note past its maturity date with no qualifying round closed gives the investor all the leverage and the founder none. The investor has the contractual right to demand cash repayment the startup has already deployed on operations.
Most investors negotiate an extension rather than force repayment but that extension happens on the investor’s terms, and they may extract lower caps, higher interest rates, or warrants as conditions. In a market where bridge rounds remain common precisely because Series A timelines have extended, founders should model what happens if the next priced round slips past the note’s maturity window.
Dilution Is Deferred, Not Eliminated
Convertible notes are sometimes mischaracterized as a low-dilution option because no equity is issued at closing. This framing is inaccurate. The note defers a valuation, not the dilution that ownership impact is concentrated at conversion and easy to underestimate.
When multiple notes with different caps, discount rates, and MFN clauses are outstanding simultaneously, the compounding dilution at Series A can be substantially higher than founders anticipated.
Three notes with three different caps produce three different per-share conversion prices at a single Series A event complexity that most founders do not model until it is too late.
Tightening Terms Are Increasing the Cost of Capital
The terms on convertible notes have moved against founders over the past 18 months. Fenwick’s Q1 2025 Venture Beacon documents a 200-300 basis point rise in interest rates on convertible notes, discount rates that reached as high as 10.5 percentage points on larger deals, and valuation caps dropping on raises above $5 million. These are not minor adjustments.
A note structured today is materially more expensive for the founder than a structurally identical note from 2021. Founders entering note negotiations in 2026 should model the cost of funding under current market benchmarks not historical ones before signing.
Complex Cap Tables Create Friction at Series A
Every convertible note with different terms, a different cap, a different discount, a different MFN clause adds a layer of complexity that accumulates quietly and becomes visible at Series A diligence.
A Series A investor’s first move is to pull the fully diluted cap table and review every outstanding instrument, because those instruments can convert into a meaningful portion of ownership at closing. Not because any single note is the problem, but because the stack of mismatched terms lands on the cap table all at once exactly when a founder needs the round to move fast.
A large overhang of convertible debt from numerous note rounds with inconsistent terms can make it genuinely difficult to run a competitive Series A process, even when business fundamentals are strong.
Convertible Notes vs. SAFEs vs. Priced Equity Rounds: 2026 Comparison
| Feature | Convertible Note | SAFE | Priced Equity Round |
|---|---|---|---|
| Legal structure | Short-term debt → equity | Contractual right to future equity | Equity issued at closing |
| Valuation required? | No | No | Yes |
| Interest accrues? | Yes (typically 2-8%) | No | No |
| Maturity date? | Yes (12-24 months) | No | N/A |
| Investor voting rights? | No (until conversion) | No (until conversion) | Yes |
| Repayment risk? | Yes, at maturity if no round | None | N/A |
| Legal complexity | Moderate | Low | High |
| Best use case | Bridge rounds, seed >$500K | Pre-seed, quick closes | Series A and beyond |
| 2026 market position | Dominant in bridge rounds | 81% of Q1 2025 deals (Fenwick) | Rare at pre-seed |
FAQ’s
The mechanics of convertible notes generate a consistent set of questions from founders, particularly around interest rates, what happens at maturity, and how notes compare to SAFEs.
The typical range is 2-8%, with 5-6% most common. Founders should budget for the higher end of this range in current deals and model the full converting amount principal plus accrued interest into their cap table projections before signing.
A valuation cap sets a ceiling on the company valuation used for conversion the noteholder converts as if the company were valued at the cap, regardless of the actual Series A valuation. A discount rate applies a percentage reduction to the Series A share price at conversion. When a note includes both, the investor receives whichever mechanism is more favorable, not both stacked.
The note is technically due and the investor has the contractual right to demand cash repayment. In practice, most investors negotiate an extension rather than force insolvency but the extension happens on the investor’s terms. Founders should begin that conversation three to six months before the maturity date, not after it passes.
SAFEs carry no interest rate and no maturity date, which eliminates the two main risks that convertible notes create for founders: accruing debt cost and a default deadline. Convertible notes retain a practical advantage in specific situations: bridge rounds between priced rounds, investors with yield-mandate requirements, and international deals in jurisdictions where the SAFE is not a recognized legal instrument.
Accrued interest adds to the principal amount that converts at the qualifying round, increasing the investor’s share count beyond what the raw principal alone would produce.
On a $500,000 note at 6% for 12 months, that is $30,000 in additional converting value, a meaningful increase in the investor’s equity stake that founders should model before signing. Interest on convertible notes is typically simple interest, accruing on the principal balance without compounding.
Manage Convertible Notes with Eqvista
A convertible note can help you raise capital quickly without setting a valuation too early, but the trade-off comes later. Interest, valuation caps, discounts, maturity dates, and multiple outstanding notes can all affect how much ownership founders give up when the notes convert. Before signing, it is worth looking beyond the cash you are raising and modeling what those terms could mean for your ownership at the next funding round.
Eqvista makes it easier to keep that picture clear. You can issue and modify convertible notes, model different conversion scenarios, and keep your cap table updated as terms change, all in one platform. If you are raising convertible notes and want to see exactly how they could affect your ownership before your next round, explore Eqvista or get started today.

Start Managing Your Equity with Eqvista
Build your cap table, manage equity, and keep ownership organized as your company grows.